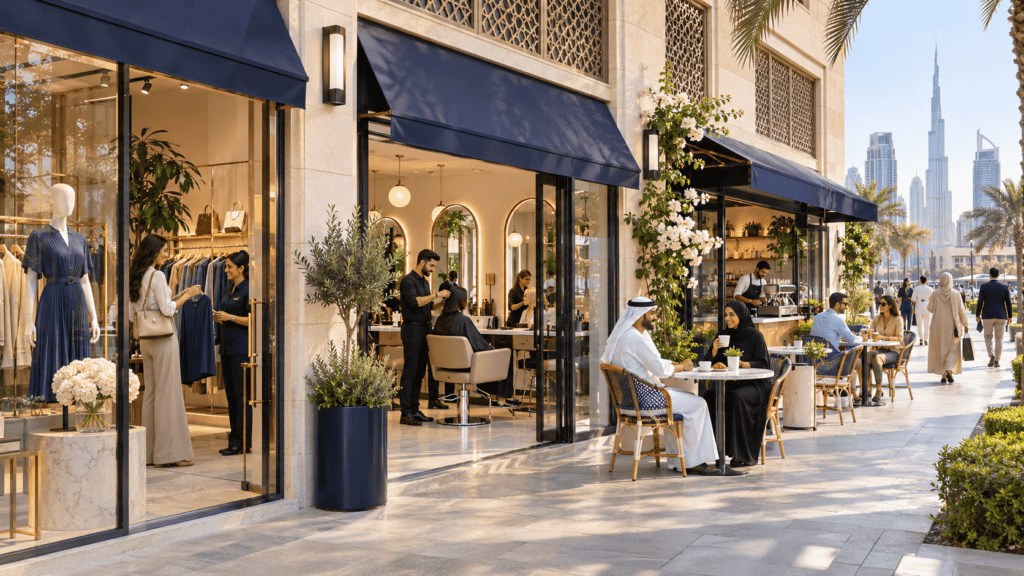
A customer slips near your café entrance. A display falls inside your shop. A visitor trips over a cable in your salon.
Everyday accidents can lead to injury claims, compensation demands and legal expenses. For a small business, handling these costs can put pressure on cash flow.
Public liability insurance in Dubai helps protect businesses against covered legal liabilities for accidental injury to third parties or damage to their property. The protection depends on your business activities, policy wording, limits and exclusions.
Here is what shop, salon and café owners should check before choosing a policy.
What Is Public Liability Insurance?
Public liability insurance covers specified legal liabilities arising from your business operations. Third parties can include customers, visitors and other members of the public.
Depending on the policy, cover may include compensation for covered bodily injury or property damage, along with legal defence costs. Legal expenses may require the insurer’s prior consent.
An accident does not automatically mean the insurer will pay. Your legal liability and the circumstances of the incident must fall within the policy’s cover.
Why Shops, Salons and Cafés Should Consider It
Businesses that welcome customers face regular exposure to accidents. Wet floors, narrow walkways, loose fixtures and trailing cables can all create risks.
The right insurance should reflect what your business actually does.
| Business | Example of a potential claim | What to check |
|---|---|---|
| Retail shop | An unsecured display falls and injures a customer | Premises liability and declared retail activities |
| Salon | A customer trips over a cable near a styling station | Premises cover and separate treatment-related risks |
| Café | A visitor slips on a spilled drink | Premises liability and any food or product liability requirements |
These examples illustrate possible exposures. Whether a claim is covered depends on the facts and policy terms.
What Can Public Liability Insurance Cover?
Accidental injury to customers or visitors
A policy may respond when your business is legally liable for a covered third-party injury.
For example, a customer could seek compensation after falling because of a hazard at your premises.
Accidental damage to third-party property
Cover may apply if your business accidentally damages someone else’s property and is legally responsible.
However, property entrusted to your business can have different exclusions. A customer’s belongings left in your care should be discussed specifically with the insurer.
Legal defence costs
A covered claim may involve solicitor fees and other defence expenses. Check whether these costs sit within the liability limit or are payable in addition to it.
Also confirm when insurer approval is required before appointing legal representatives or incurring expenses.
Important Cover Checks for Each Business
For shops: declare products and activities accurately
Tell the insurer what you sell and whether you offer installation, repairs, demonstrations or deliveries.
An injury caused by a product you sell can raise a different liability exposure from an accident inside the shop. Ask whether product liability is included or available separately.
For salons: check treatment liability
Do not assume that public liability insurance covers injuries arising from hair colouring, waxing, facials or other treatments.
Ask the insurer to confirm cover for your exact services, including any treatment liability or professional liability requirements. Disclose all treatments, equipment and products used.
Medical aesthetic procedures need particular attention when arranging suitable insurance.
For cafés: check food, drinks and outdoor seating
A slip inside a café and an illness allegedly caused by food are different types of claim.
Ask whether food and beverage liability is covered under the proposed policy. Product liability can be an optional cover rather than an automatic inclusion.
Also declare outdoor tables, takeaway operations, catering, deliveries and activities away from your main premises.
What Should You Avoid Assuming Is Covered?
Public liability insurance is one part of a business insurance programme. Check the wording carefully for:
Employee injuries: Review workmen’s compensation and employers’ liability requirements separately.
Damage to your own assets: Your stock, furniture, equipment and fit-out need suitable property cover.
Treatment or professional errors: These may require specific liability protection.
Product-related claims: Confirm whether product liability is included.
Property in your care: Customer belongings or items being worked on may be restricted or excluded.
Contractual obligations: A lease or client contract may impose responsibilities beyond the policy’s cover.
You can also read our guide to professional indemnity vs public liability insurance in the UAE to understand how these policies address different exposures.
Is Public Liability Insurance Mandatory in Dubai?
Check the requirements that apply to your specific business, premises and licensing authority.
Your landlord, shopping mall, free zone or commercial contract may require insurance with a particular liability limit or wording. Before buying, share the relevant insurance clause with your broker and ask them to confirm whether the proposed cover meets it.
Avoid choosing a policy based only on the business name or premium.
How Much Cover Does Your Business Need?
The appropriate liability limit depends on your activities and potential exposure.
Consider:
The number of customers visiting your premises.
The nature of your products or services.
Your location and neighbouring businesses.
The potential severity of an injury or property-damage claim.
Requirements in your lease or contracts.
Your claims history and any additional locations.
Check whether the limit applies per occurrence, in total for the policy period, or both. Also review excesses and any lower limits for specific extensions.
What Affects the Premium?
Insurers may assess your business activity, turnover, premises, claims history, requested limit and additional covers.
When comparing quotations, review the cover alongside the price. A cheaper quotation may have a higher excess, narrower activities or missing extensions.
For businesses with several insurance needs, explore whether a suitable package can combine property and liability protection. Visit our business insurance in the UAE page to review available options.
What Information Should You Prepare for a Quote?
Having the following details ready can help the insurer assess your requirements:
Trade licence and full business activities.
Premises address and details of each location.
Annual turnover and employee count.
Description of products, treatments or services.
Previous claims or known incidents.
Required liability limit.
Insurance requirements from your landlord or contracts.
Details of deliveries, catering or other off-site work.
Accurate information helps reduce gaps between your actual operations and the activities shown on the policy.
What Should You Do After an Accident?
First, arrange appropriate assistance for anyone injured and make the area safe.
Record the incident, preserve relevant photographs or CCTV, and collect witness details where appropriate. Notify your insurer or broker promptly in line with the policy conditions.
Avoid admitting liability, promising compensation or agreeing to a settlement without the insurer’s approval.
Frequently Asked Questions
Does a small shop need public liability insurance?
Even a small shop can face customer injury or property-damage claims. Review your exposure alongside any landlord, licensing or contractual requirements.
Does public liability insurance cover salon treatment injuries?
Do not assume it does. Ask for written confirmation that your specific treatments are covered and whether additional treatment or professional liability insurance is needed.
Does it cover food poisoning claims against a café?
Cover depends on the policy. Confirm whether food-related claims fall within the product liability or other relevant section, including its exclusions and limits.
Can one policy cover multiple branches?
An insurer may arrange cover for multiple locations. Ensure every branch and its activities are declared and included in the policy.
Does it cover damage to my shop or café equipment?
Public liability insurance addresses covered third-party liabilities. Your own equipment, stock and fit-out require appropriate property insurance.
Can I buy public liability insurance as part of a package?
Some insurers offer business packages combining liability with other covers. Compare the individual sections, limits and exclusions before choosing.
Compare Cover for Your Dubai Business
Your insurance should reflect how your business operates—from the products you sell to the treatments you provide and the customers you welcome.
InsurancePolicy.ae helps businesses compare suitable insurance options based on their activities and requirements.
Request a business insurance quotation and share your trade licence, business details and any landlord insurance requirements with our team.
Related Readings
Professional Indemnity vs Public Liability Insurance in the UAE
Business Insurance in the UAE: Commercial Insurance Solutions
Coverage is subject to the insurer’s underwriting acceptance, policy wording, declared activities, limits, excesses and exclusions.